

I promise this introduction won’t be as long as the last one about weather.
But please indulge me for 90 seconds.
So, a little more than 100 years ago, this woman Henrietta Leavitt was doing the tedious work of measuring how bright thousands of stars were on photographic plates (these were the predecessor to film as a way to capture images). She noticed a behavior in a particular class of pulsing stars that effectively said, the slower these stars pulsed, the brighter they were intrinsically.1
This probably seems marginally interesting today, like ok cool I guess. But at the time astronomers couldn’t tell the difference between a dim star that was close to the Earth and a bright star that was far away. For them, both of these things produced the same kind of smudge on photographic plates. Apparent brightness was a messy mix of these two variables: how luminous the thing really is & how far away it sits.
Henrietta’s work broke these two things apart and meant that if you could observe the pulse rate then you knew its true luminosity and if you knew its true luminosity then you could back out the distance from how dim it appeared. The name astronomers gave to this was “standard candles”.
A few years later, a guy named Edwin Hubble found one of these pulsing stars, ran Leavitt’s math and discovered that the thing he was observing, which he thought was a gas cloud in our galaxy, was actually an entire separate galaxy a million light years away. So the TLDR is that the observable universe got roughly a trillion times larger because one person figured out how to separate what something looks like from what it actually is.
This is very cool on its own obviously.
But the other interesting thing is that around the same time there were a pair of other astronomers who independently made a scatter plot charting true luminosity on one axis and temperature on the other. They found that stars aren’t randomly distributed across that space and instead cluster into families. The implication here being that stars with identical apparent brightness can and do sit in completely different families with completely different pasts and most importantly completely different futures…
So What Is Written In The Stars?
There’s been a lot of discourse around markets, narratives, capital, company-building and financial nihilism over the past few years. It feels like it’s reaching some sort of fever pitch as the technology and financial worlds reckon with a future that appears vastly different from the one of the previous few decades. It seems especially true that disentangling progress from asset prices has become noisier and in many ways more reflexive. But as investors who are in the business of buying things that will (hopefully) outperform, a simplistic framing is:
Forward returns ~= fundamental growth x multiple change (x the payout you collect along the way)
In this case, the multiple maps quite cleanly to the smudge on the photographic plates. It’s an observable data point that’s entangling a pair of things that the market can’t directly see, which is how good the business actually is and how far away (or durable) its future cash flows sit. I would argue that most of the money to be made comes from investors best equipped to un-entangle those two variables before everyone else does (variant perception) and that we will continue to see spectacular capital destruction from investors who confuse the smudge for the star.
Value Investing != Fundamental Investing
I believe there’s a somewhat misunderstood belief that fundamental investing historically dominated in terms of generating outsized returns. Mostly this lore is a function of Graham, Buffett, the Tiger lineage and a lot of narrative-building around this cohort. The belief is that sometime in the 2000s this stopped working and anyone investing this way got railroaded by momentum, trend and just-buy-the-tech-giants. The conclusion was (is?) that “fundamentals are dead”.2
This is partly true.
If you look at historical data, the academic value factor (long cheap stocks, short expensive ones) delivered a real & persistent premium from 1926 to around 2006.3 But since 2007 it has been completely massacred, with its longest and deepest drawdown in the factor’s recorded history. Almost the entirety of this can be explained by the widening valuation gap between growth and value (i.e. cheap stocks getting relatively cheaper).
I say it is only partly true though because the idea that fundamental investing was synonymous with this strategy is a bit of a fictional narrative. First of all, momentum is not a new thing and trend following has worked across every asset class for more than a hundred years.4 These strategies have always been competitive with value but they didn’t benefit from the same cast of characters5 to point to and so the dominance of “fundamental investing” is partly a dominance of storytelling and narrative.
The perhaps obvious explanation though is that value investing and fundamental investing are not the same thing. The last 15-20 years certainly killed one of them (for now) but fundamentals haven’t gone anywhere.
The modern version of “fundamentals don’t matter” isn’t stupid per se. It’s rooted in a lot of the ideas that many of us at Compound have written about before. The largest companies receive the largest mechanical bid, there are winner-take-most economics in software, AI means the giants can convert their scale into moats faster than challengers, and there are microstructure reasons that momentum has become embedded more in our market infrastructure. These are all real. By the same stroke though, what we know as the Mag 7 today outperformed because they compounded actual earnings at rates that repeatedly justified and then re-justified their multiples. Today, in August 2026, there’s at least some belief that we are in/entering a new AI acceleration era, one where the labs & hyperscalers with the capital to source & purchase compute at-scale will pull irreversibly away.6 Don’t bother with valuation work, don’t bother with asking how much of the growth has been pulled forward, don’t ask how large the economy must become to support expectations across the board. Just own a couple names and ride the new technological paradigm because fundamentals are a larp for people who miss the old world.
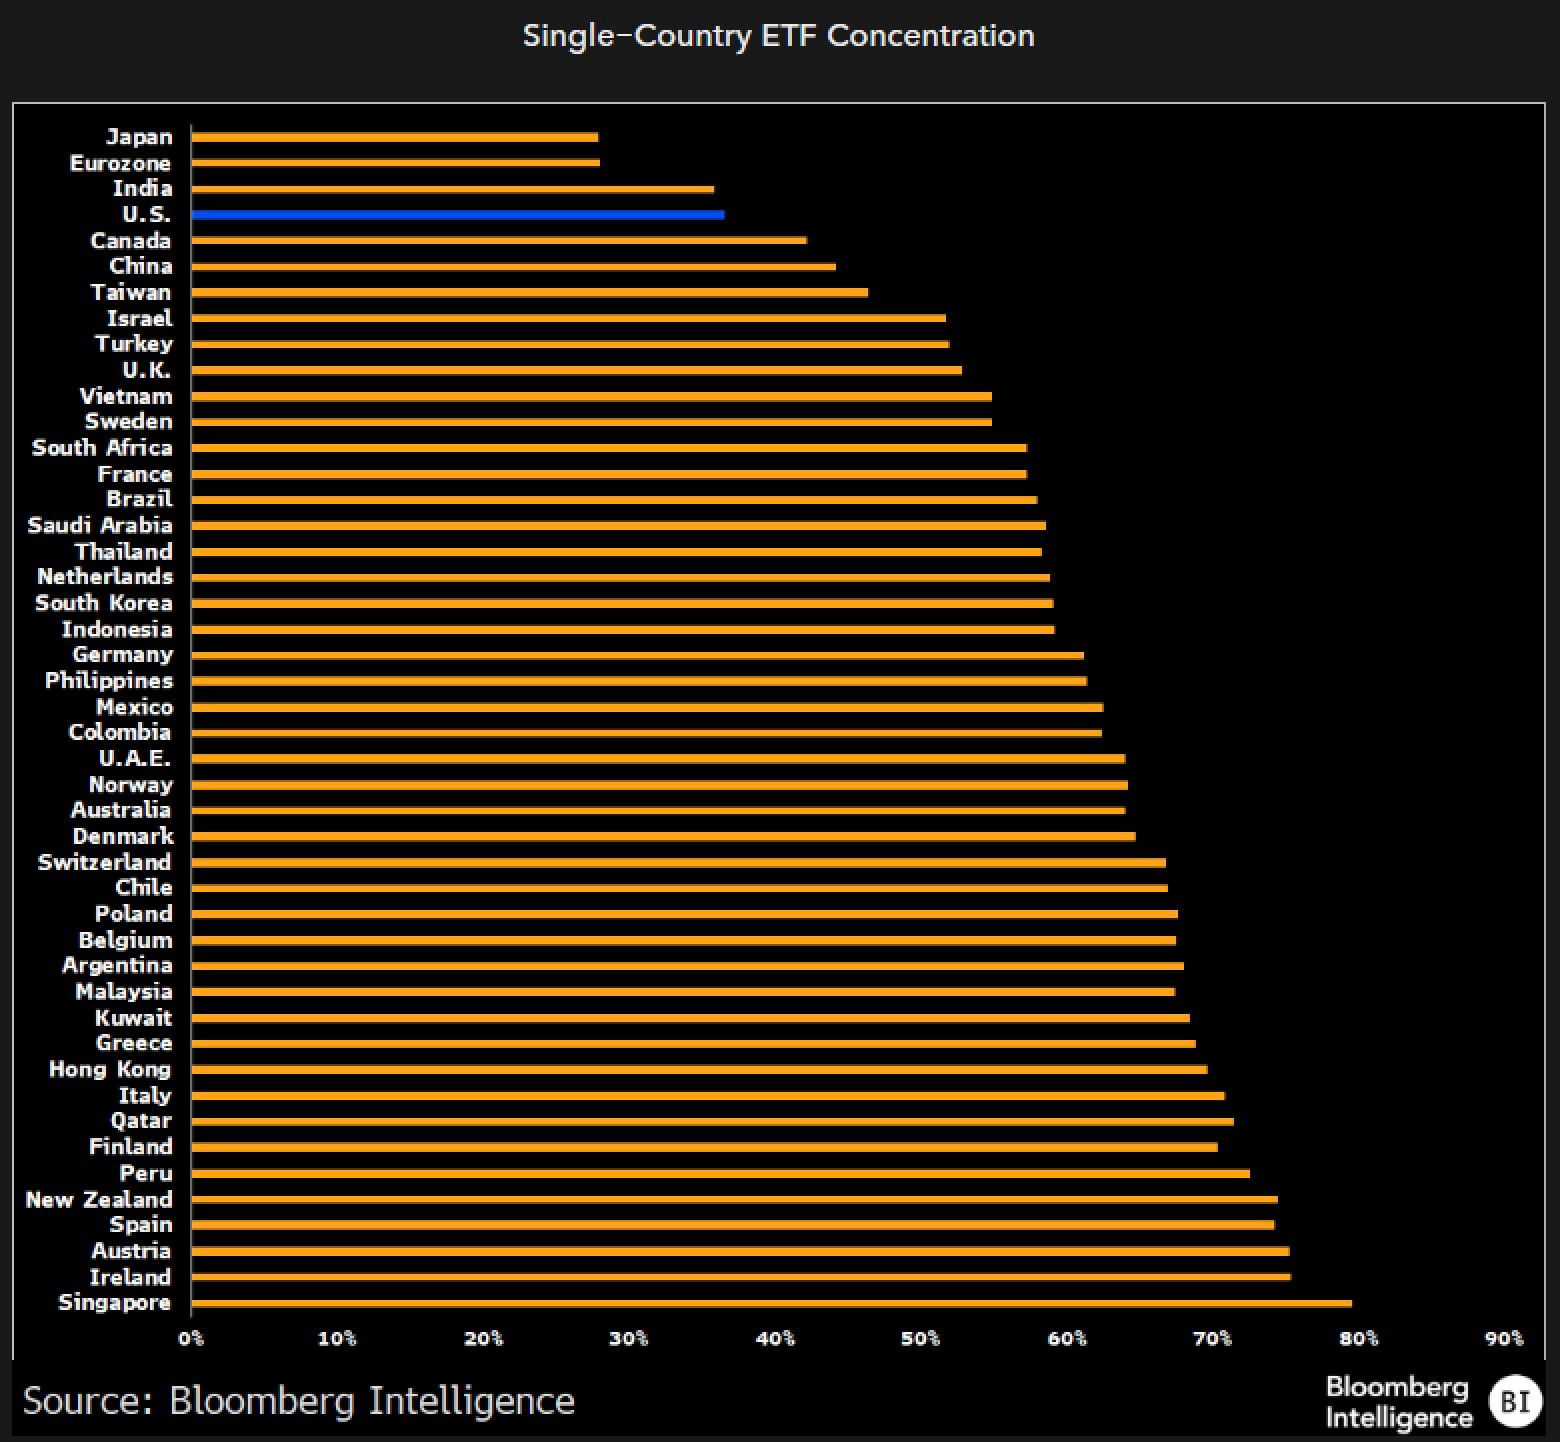
I even think that despite people fear-mongering about how concentrated the top of the equity markets have become, there’s still a lot of room for this to grow.7 So to kind of preemptively argue against myself here, I don’t think saying “it’s already at peak power-law levels” is that strong of an argument on its own.8
Despite this, the conclusion I laid out above — own the giants as they go from $1-4T companies into $10-20T ones — has a lot of baked-in flaws.
For one, this reasoning has been tried over and over and has a pretty measured track record of underperformance9. Critics of this thinking will say “you don’t get it”, “this is the first time we’re solving intelligence”, “AGI”, “computer God”, “Do you think Jensen Huang, Elon Musk, Sam Altman are all wrong and you understand businesses and the world better than them?”. This is a Pandora’s Box for another time but definitionally any truly transformative technology is going to invite the types of hyperbolic predictions that now have a giant social media engine to fan the flames. Also, I largely agree that most jobs are made up and we will keep making up new ones.10
Markets Are Becoming Less Efficient
We also consistently see even these massive, constantly analyzed & picked-over companies mispriced by incredible amounts. Meta is one of the most covered companies on the planet with an effective oligopoly in almost every market it operates in, and during the second half of 2022 traded at ~8x forward earnings. It was priced like a melting ice-cube and then ripped 8x+ in people’s face after this. This entire move was a valuation event where there was huge fundamental disagreement about a company everyone knew everything about.
And maybe the most poignant point here is that this increasingly popular underlying belief in and of itself is the setup. I spammed some thoughts recently but the TLDR is that Silicon Valley’s increased influenced on financial markets has warped a lot of how they function and how participants behave. Too many people are now rushing to the other side of the boat.11
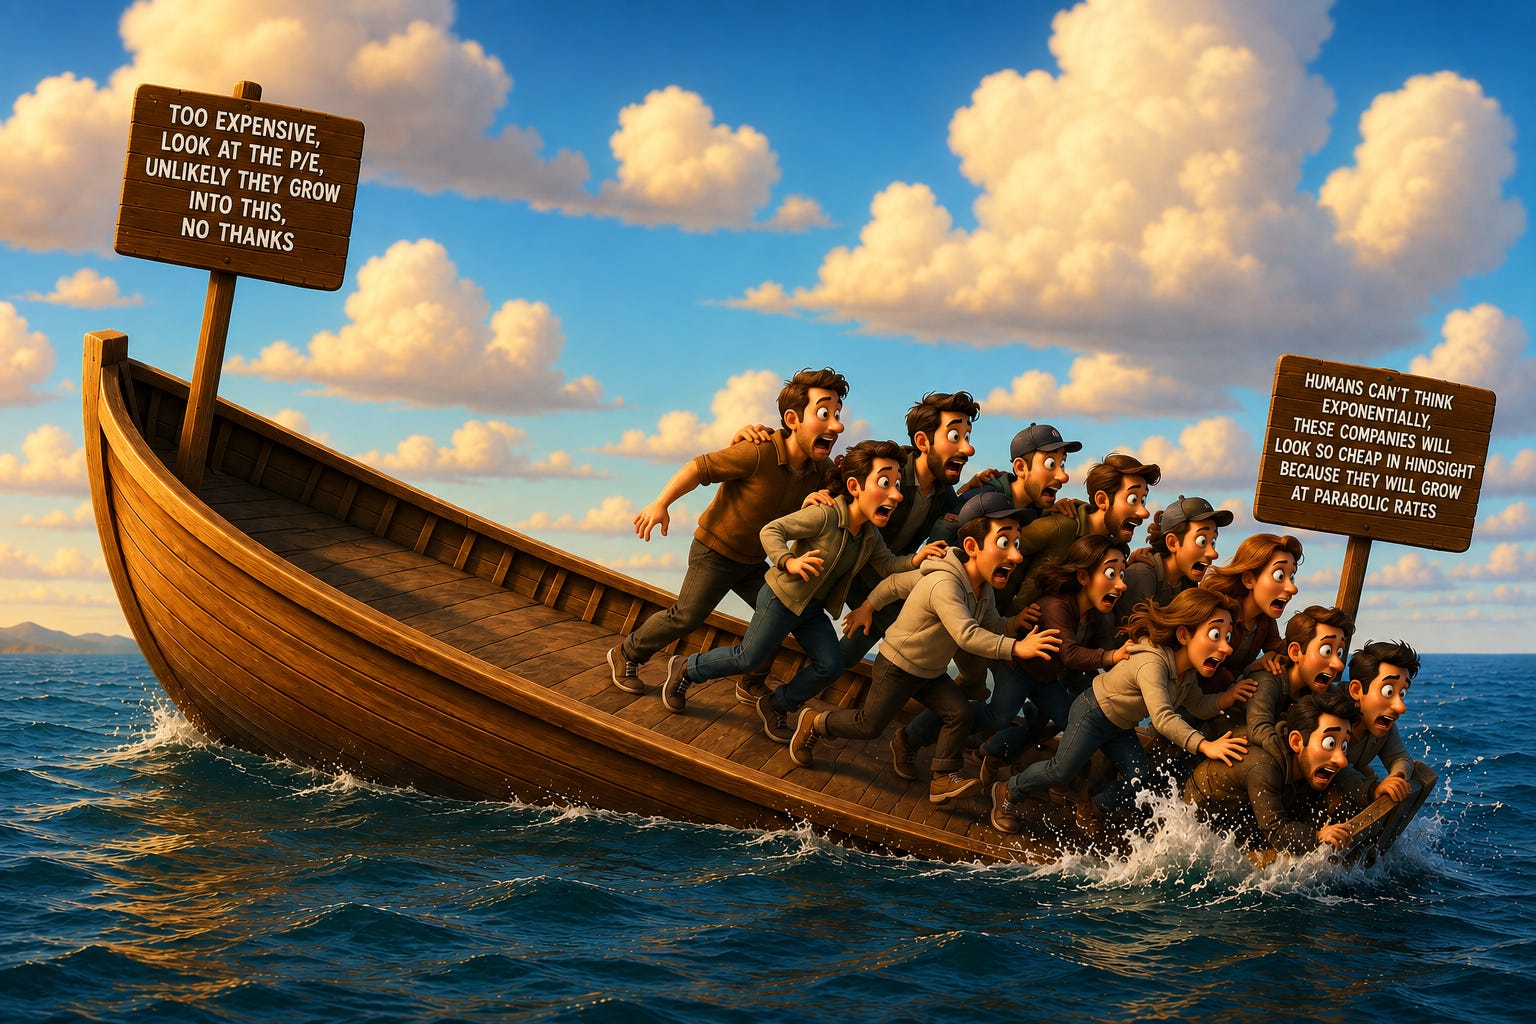
Alpha is paid out of other people’s errors or misjudgments. “Fundamentals are dead” has become a consensus position. I would argue the degree to which narratives impact security pricing was not well understood by a lot of the investing class up until recently. But as the SV complex has established a prominent position within broader financial markets, this position is no longer novel. Now the dumbest person you know tries to signal their cleverness by parroting that “everything is a meme”.
Many fundamental L/S managers have been washed away in favor of those who bought the QQQs fifteen years ago or systematic pod-shops. It’s at least worth considering that as consensus builds around the idea that any kind of variant perception is a waste of time, it might be a nice time to lean against that.
An aside: I like listening to Gavin Baker but I did a bit of a double-take on his most recent pod when he claimed everyone he spoke to on his trip is more bullish than he is. It’s not that I don’t believe him. In fact, it matches mine and many others experience visiting that city. But there is a clear disconnect when he suggests that there is not a single data point that isn’t bullish. It also came on the heels of memory stocks nuking 50%. And this is kind of what I’m getting at which is that lots of things can be true at the same time — he may see insatiable long-term demand and companies trading at “relatively cheap” forward earnings and yet, the multiples of many companies could just as easily compress in the interim because the market has pulled forward expectations.
It would be naive (arrogant) for me to suggest market discounts are usually wrong. I tend to believe there is quite a bit of signal in price and that there’s a strong onus on me (or any other investor) to disprove that baseline. Incidentally I do also believe markets are becoming less efficient in the short term. But most of the time companies that are “cheap” are cheap for a reason. And most companies that become expensive generally fail to grow into those forward expectations. And so there’s this constant tension that exists when trying to evaluate the forward returns at any given time.12
The Perception Matrix
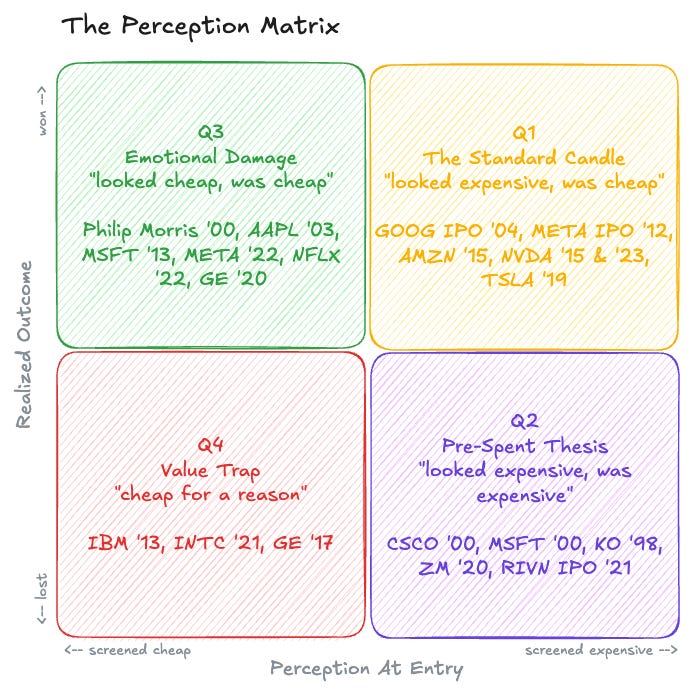
Quadrant 1 (Q1): Looked expensive at the time, was actually cheap in hindsight.
Quadrant 2 (Q2): Looked expensive at the time, was.
Quadrant 3 (Q3): Looked cheap at the time and actually was too cheap.
Quadrant 4 (Q4): Looked cheap and was cheap for a reason. The canonical value-trap.
What’s probably most interesting about this broad framing is that companies can be time-stamped. What I mean by this is that you can populate this matrix (we will below) with the same businesses and drop them in different quadrants based on different moments in time. Watching how those companies move across quadrants is instructive. Microsoft at 60x in December of 1999 and Microsoft at 10x in 2013 share the same ticker obviously but they for sure should not sit in the same quadrant.
Another obvious thing to point out is that the outcome axis measures what you paid, which is a very different thing than how the company executed. This is a lesson many in the crypto community know all too well at this point (hopefully). The quadrants are an expression of the gap that exists between the embedded expectations and the forward delivered reality.13
We will come back to this point.
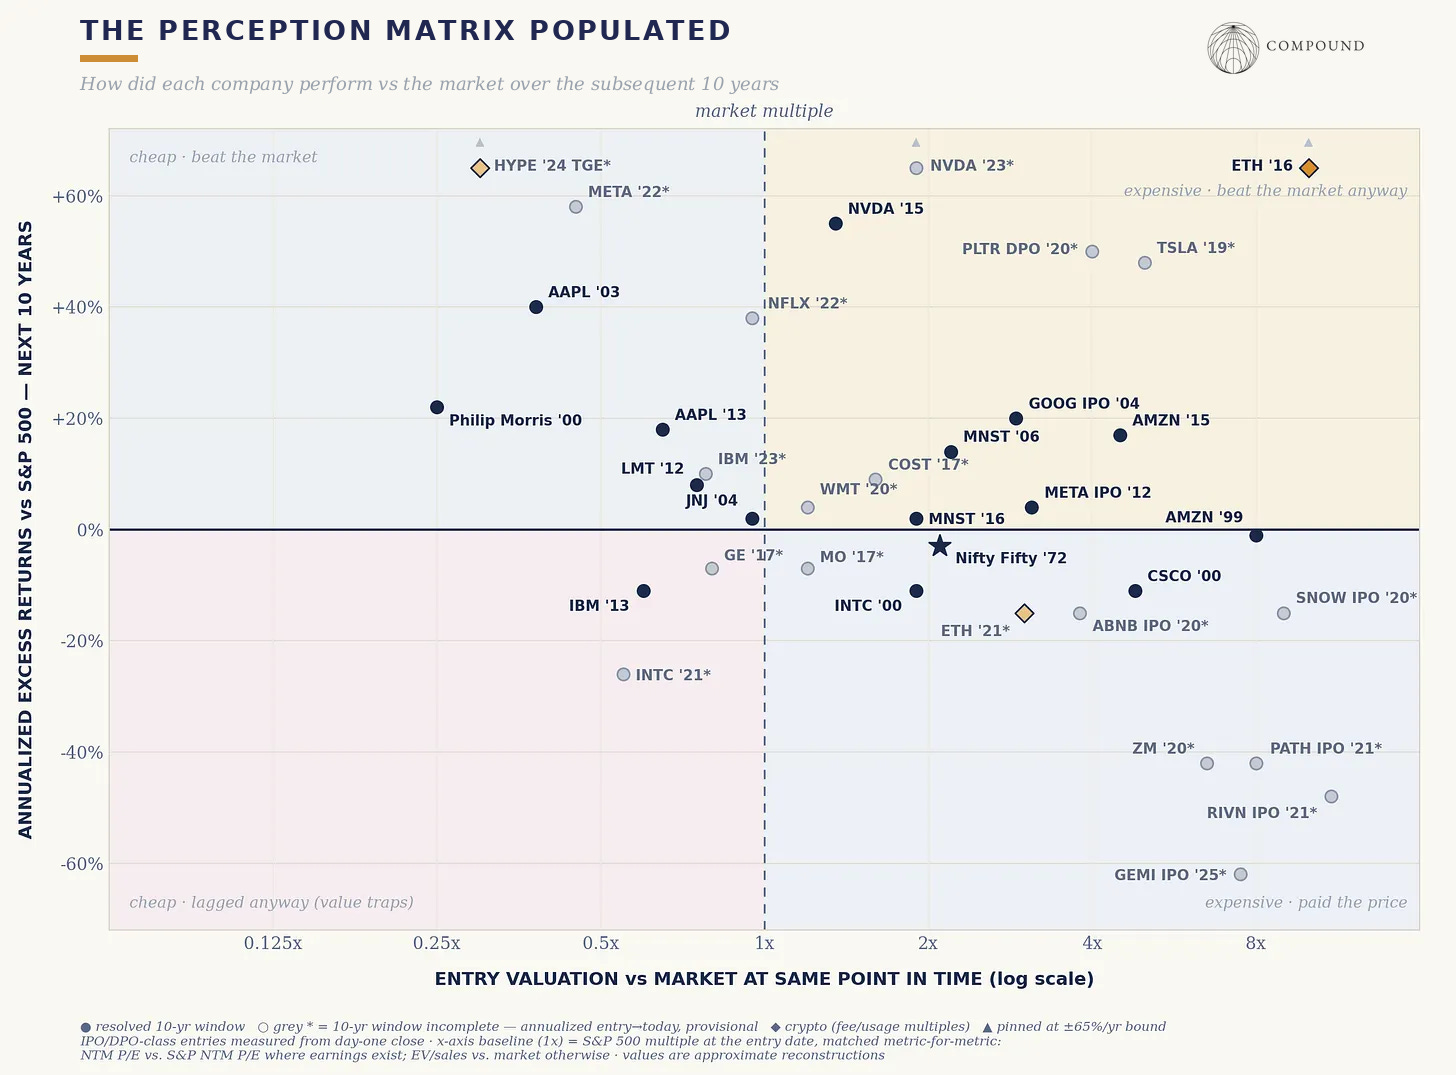
It’s worth staring at this chart for a bit just to familiarize yourself with what it is showing and maybe come to your own immediate first impressions. I’ve chosen my own sample of companies across industries with an obvious bend towards technology. But I also designed a mini-game you can play here that has a much wider set of companies across history.
We could sit here all day and observe individual company comparisons that cluster in similar spots. Cisco in 2000 and Amazon in 2015 both sit way out on the expensive right tail. One of them was a 25-year round trip and the other beat the (historically great bull) market by ~8 points a year. NVDA in 2015 & Intel in 2000 both screened roughly around the prevailing market multiple at the time. One of them compounded at ~50% above market annually for a decade while the other lost investors ~60% over the following 10 years.
What’s In A Quadrant
Quickly unpacking each of these…
Q1: Looked expensive at the time, was actually cheap in hindsight
This is the quadrant du jour. This is where every venture investor wants you to believe their most important companies live. Some of course do, and we will all find out together which ones those are in the future. But SV’s increased importance means we should interrogate what that means for asset pricing composition.
If the techno-optimist had much less say 15-20 years ago, then is it likely there was a large opportunity to benefit from owning assets that perhaps were priced on under-appreciated growth assumptions? If we were in the midst of a transition away from atoms and toward bits, then anticipating a more rapid adoption of software relative to consensus was a huge advantage. But as that belief system spreads and more capital allocators bend toward a “more-growth-than-you-think” attitude, at some point the expectations become too great. Or at least, the demand for immediate observation of those increased growth expectations becomes unreasonable.
My belief is that we’ll see fewer companies in this particular quadrant than we have in the past, and by extension we’ll see more in Quadrant 2.
The reason this space is so intoxicating is because the best businesses of all time cluster here. Oftentimes it seems that comes as a business is fundamentally changing state.
Amazon in 2015. Tesla mid-2019. Nvidia as recently as May 2023.14
There is also a very specific set of other companies whose defining feature was that they looked perpetually expensive for 10+ years and in hindsight turned out to be wildly cheap the entire time.
HEICO — sells replacement jet parts. Has spent the better part of two decades trading between 25-40x earnings which is a multiple typically reserved for hypergrowth companies. Yet it’s compounded ~20%+ for decades
Old Dominion — trucking company that traded at 25-30x while its peers traded closer to 10-14x. ODFL is up ~20x since 2012 as it keeps improving margins and network density
Constellation Software — obviously a company that has been shellacked as part of the recent software sell-off but this is a company that has done a 200x in public markets and spent the last decade trading at 30-40x FCF
Monster Beverage — maybe the single best stock of the modern era in my opinion
The consistent theme here is that for businesses with long reinvestment runaways at high incremental returns, the consensus is often systematically applying a mean-reverting prior to multiples (i.e. 35x compresses to 25x) which can leave them perpetually one revision behind the underlying earnings compounding (assuming the reinvestment machine keeps converting ofc).
Q2: Looked expensive at the time, was indeed expensive
This just intuitively feels like the place that we’ll see a lot of companies gravitate towards as AI torches previously defended margins for specific types of companies. Cisco is the poster-child. The internet thesis was right and Cisco executed: revenue grew from ~$12.5B to $57B, NI surpassed its 1999 high by 2003 and earnings compounded at ~14% annually through the 2000s. And yet, the stock didn’t reclaim its March 2000 price until December 2025.15
This section is often populated by directionally correct theses just with an attached price that has already pulled forward a lot of that future reality. Microsoft in 2000 is a kinder version of Cisco but that 60x compressed to the teens and shareholders lost an entire decade of returns as a result. Coca-Cola is a non-tech version of the same story.
The 2020-2021 vintage was an orgy for this company shape. Snowflake. Zoom. Beyond Meat. Peloton. There are quite a few more. Generalizing a bit here but the common error here is just failing to interrogate the entire chain of relevance. We tend to get caught up in the pace or scale of the market and its future.
“The internet will be huge” (true) —> does not translate to “Cisco at 130x forward earnings is a buy”
“Remote work will be permanent” (partially true) —> does not translate to “Zoom at 60x”
“Perps will eat into CEX volume” (true) —> does not translate to dydx winning the category
There’s at least some tell here that if the bullish case is dominated by the category argument and the defense of valuation is fuzzily around TAM, that’s leaving a lot to be desired from an analysis perspective. Somebody in the room needs to be asking the question of what the current price is already implying.
Q3: Looked cheap at the time and actually was too cheap.
Probably the least interesting to most reading this if I’m being honest. But also weirdly relevant now that cigarettes are making a comeback? The best-performing stock in the S&P 500 from its inception (1957) through 2003 was Philip Morris. And yet, the single best entry came at peak hate during their litigation apocalypse where the company traded down to ~6-7x earnings (while carrying a ~9% dividend yield). It was basically being priced to die.
This is a tricky place to play because it feels like a lot of these types of companies are either boring in the sense that they have stable’ish cash flows with some meaningful capital-return math. But one needs to be incredibly precise on what catalyst will drive marginal buyers to them.
Apple 2013 — ~10x earnings (not even considering if you stripped the cash pile out then) because people decided the iPhone was part of a hardware cycle destined for commoditization. Einhorn (and then Icahn) laid out the now-obvious case around retention & ecosystem lock-in and the degree to which the b/s could retire a massive share of the float
Microsoft 2013 — there was a period here people thought they were the next IBM
Exxon 2020 — got kicked out of the Dow (lol), was priced for some sort of accelerating-into-terminal-decline scenario and has nearly 5x’ed against the company that replaced it in the Dow since (Salesforce)
Meta 2022 — covered this one a bit earlier
I think there is probably another shape that companies who end up here fit, which is tied to some sort of despair. Arguably Philip Morris maybe fits that bill (peak smoking-is-evil point) but other things like AMD, Domino’s, Carvana. Solana at the end of 2022 is another example. Even Hyperliquid at TGE screened outright cheap.
For this group, the consensus error seems to lean toward the market extrapolating a temporary emotional state as some sort of new fundamental reality. That could be any number of things but for these examples it was disgust (tobacco, oil) and trauma (FTX blow-up, Meta all of 2022). It’s also likely the one most impacted by career risk in some sense; if owning these things feels embarrassing to others it’s perhaps some signal.
Q4: Looked cheap and was cheap for a reason.
Many such cases. IBM 2013 is the canonical modern day example. Revenue just declined year after year and in a cruel twist the buyback that enticed a lot of investors was in retrospect just management using shareholder money to fight gravity. Intel in 2021 was not dissimilar. There’s been infinite pieces written about this dynamic specifically so I won’t add to that here.
Decomposing All Of This
This again comes back to the earlier equation:
Forward returns ~= fundamental growth x multiple change (x the payout you collect along the way)
Each entry in the matrix is some sort of tension between the first two terms. Over shorter durations, the multiple term dominates the variance, which is why these markets can feel purely narrative driven. But as we stretch the time horizon out, the fundamental term takes control.
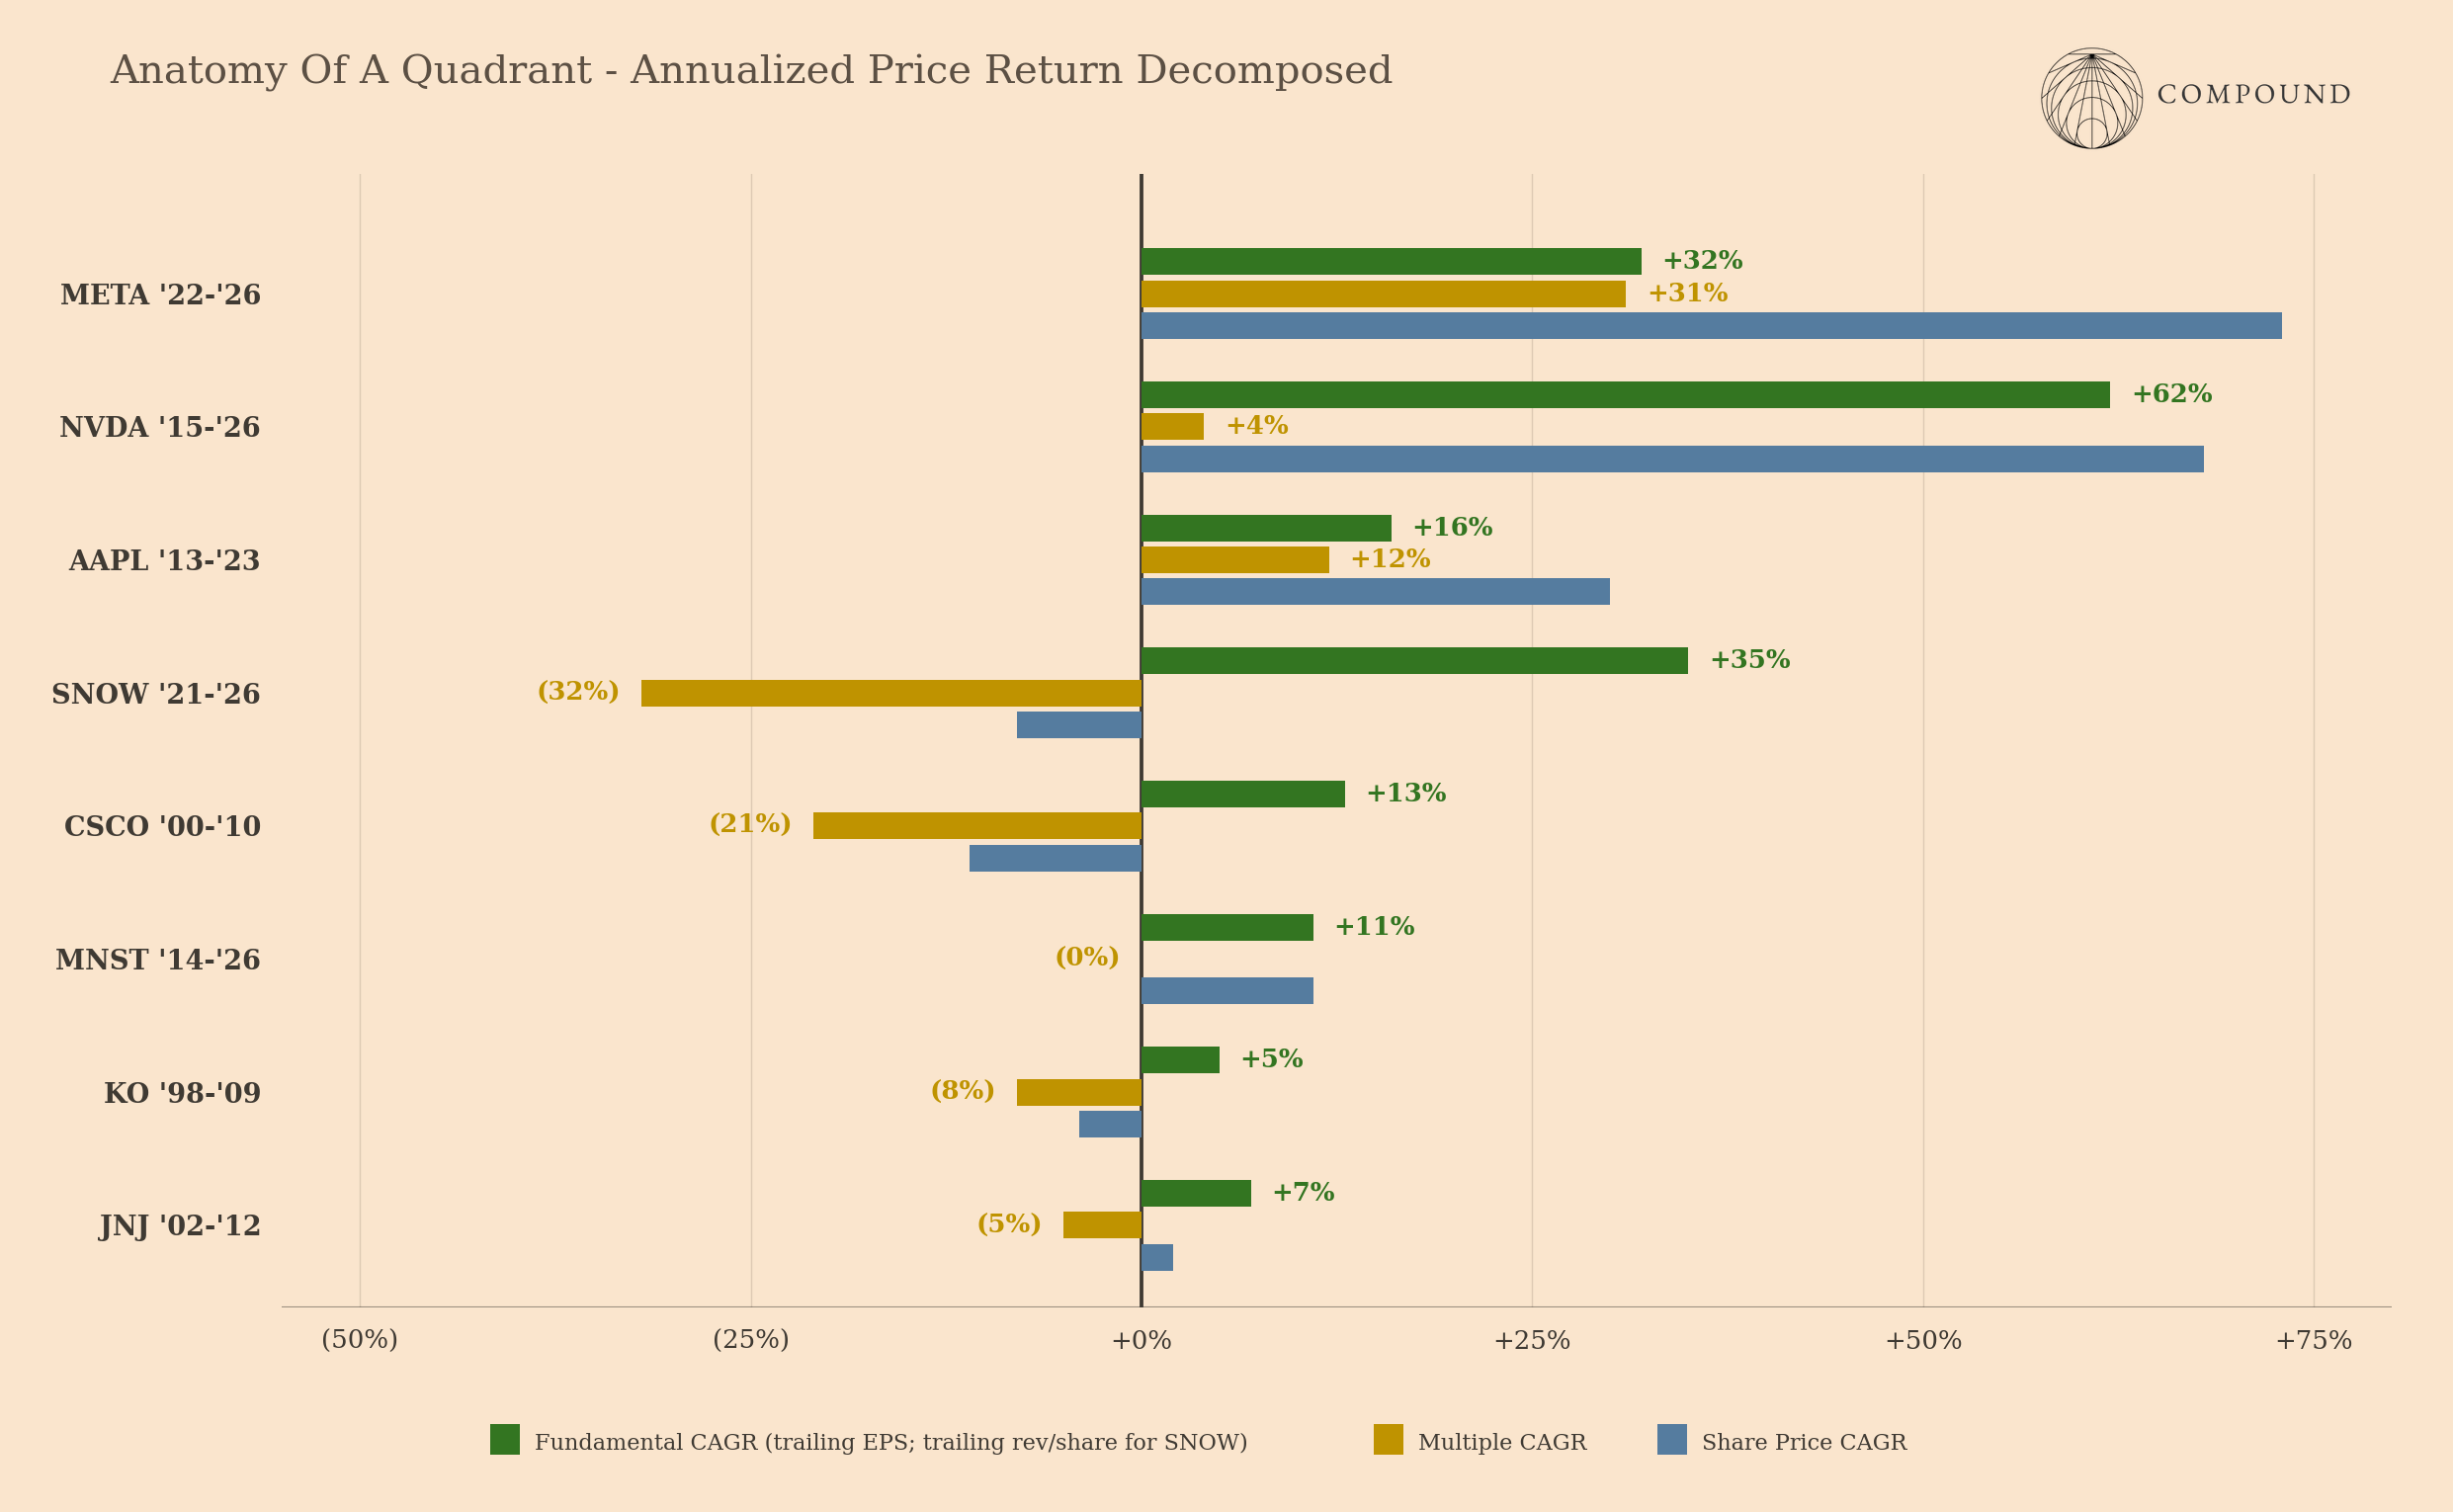
Some observations:
I don’t think it’s a coincidence that the pure multiple-victims cluster (many examples of companies like Cisco & Microsoft ~2000 and Snowflake & Zoom ~2021) — positive fundamental bars but horrifically negative multiple contraction just means the entry price had pulled forward all that and more.
NVDA ‘15 is the purest earnings story on this chart
Double-dipping is where you get violent outperformance (Apple ‘13, Microsoft ‘13, Meta ‘22) with earnings growth and multiple re-rating
Coca-Cola and Johnson & Johnsons are pretty brutal flatliners when the equity markets are compounding at the rates they were during those periods
That said, it’s worth pointing out you can still see assets win despite persistently compressing multiples so long as the fundamental long-term earnings growth continues to pay that “de-rating” toll.
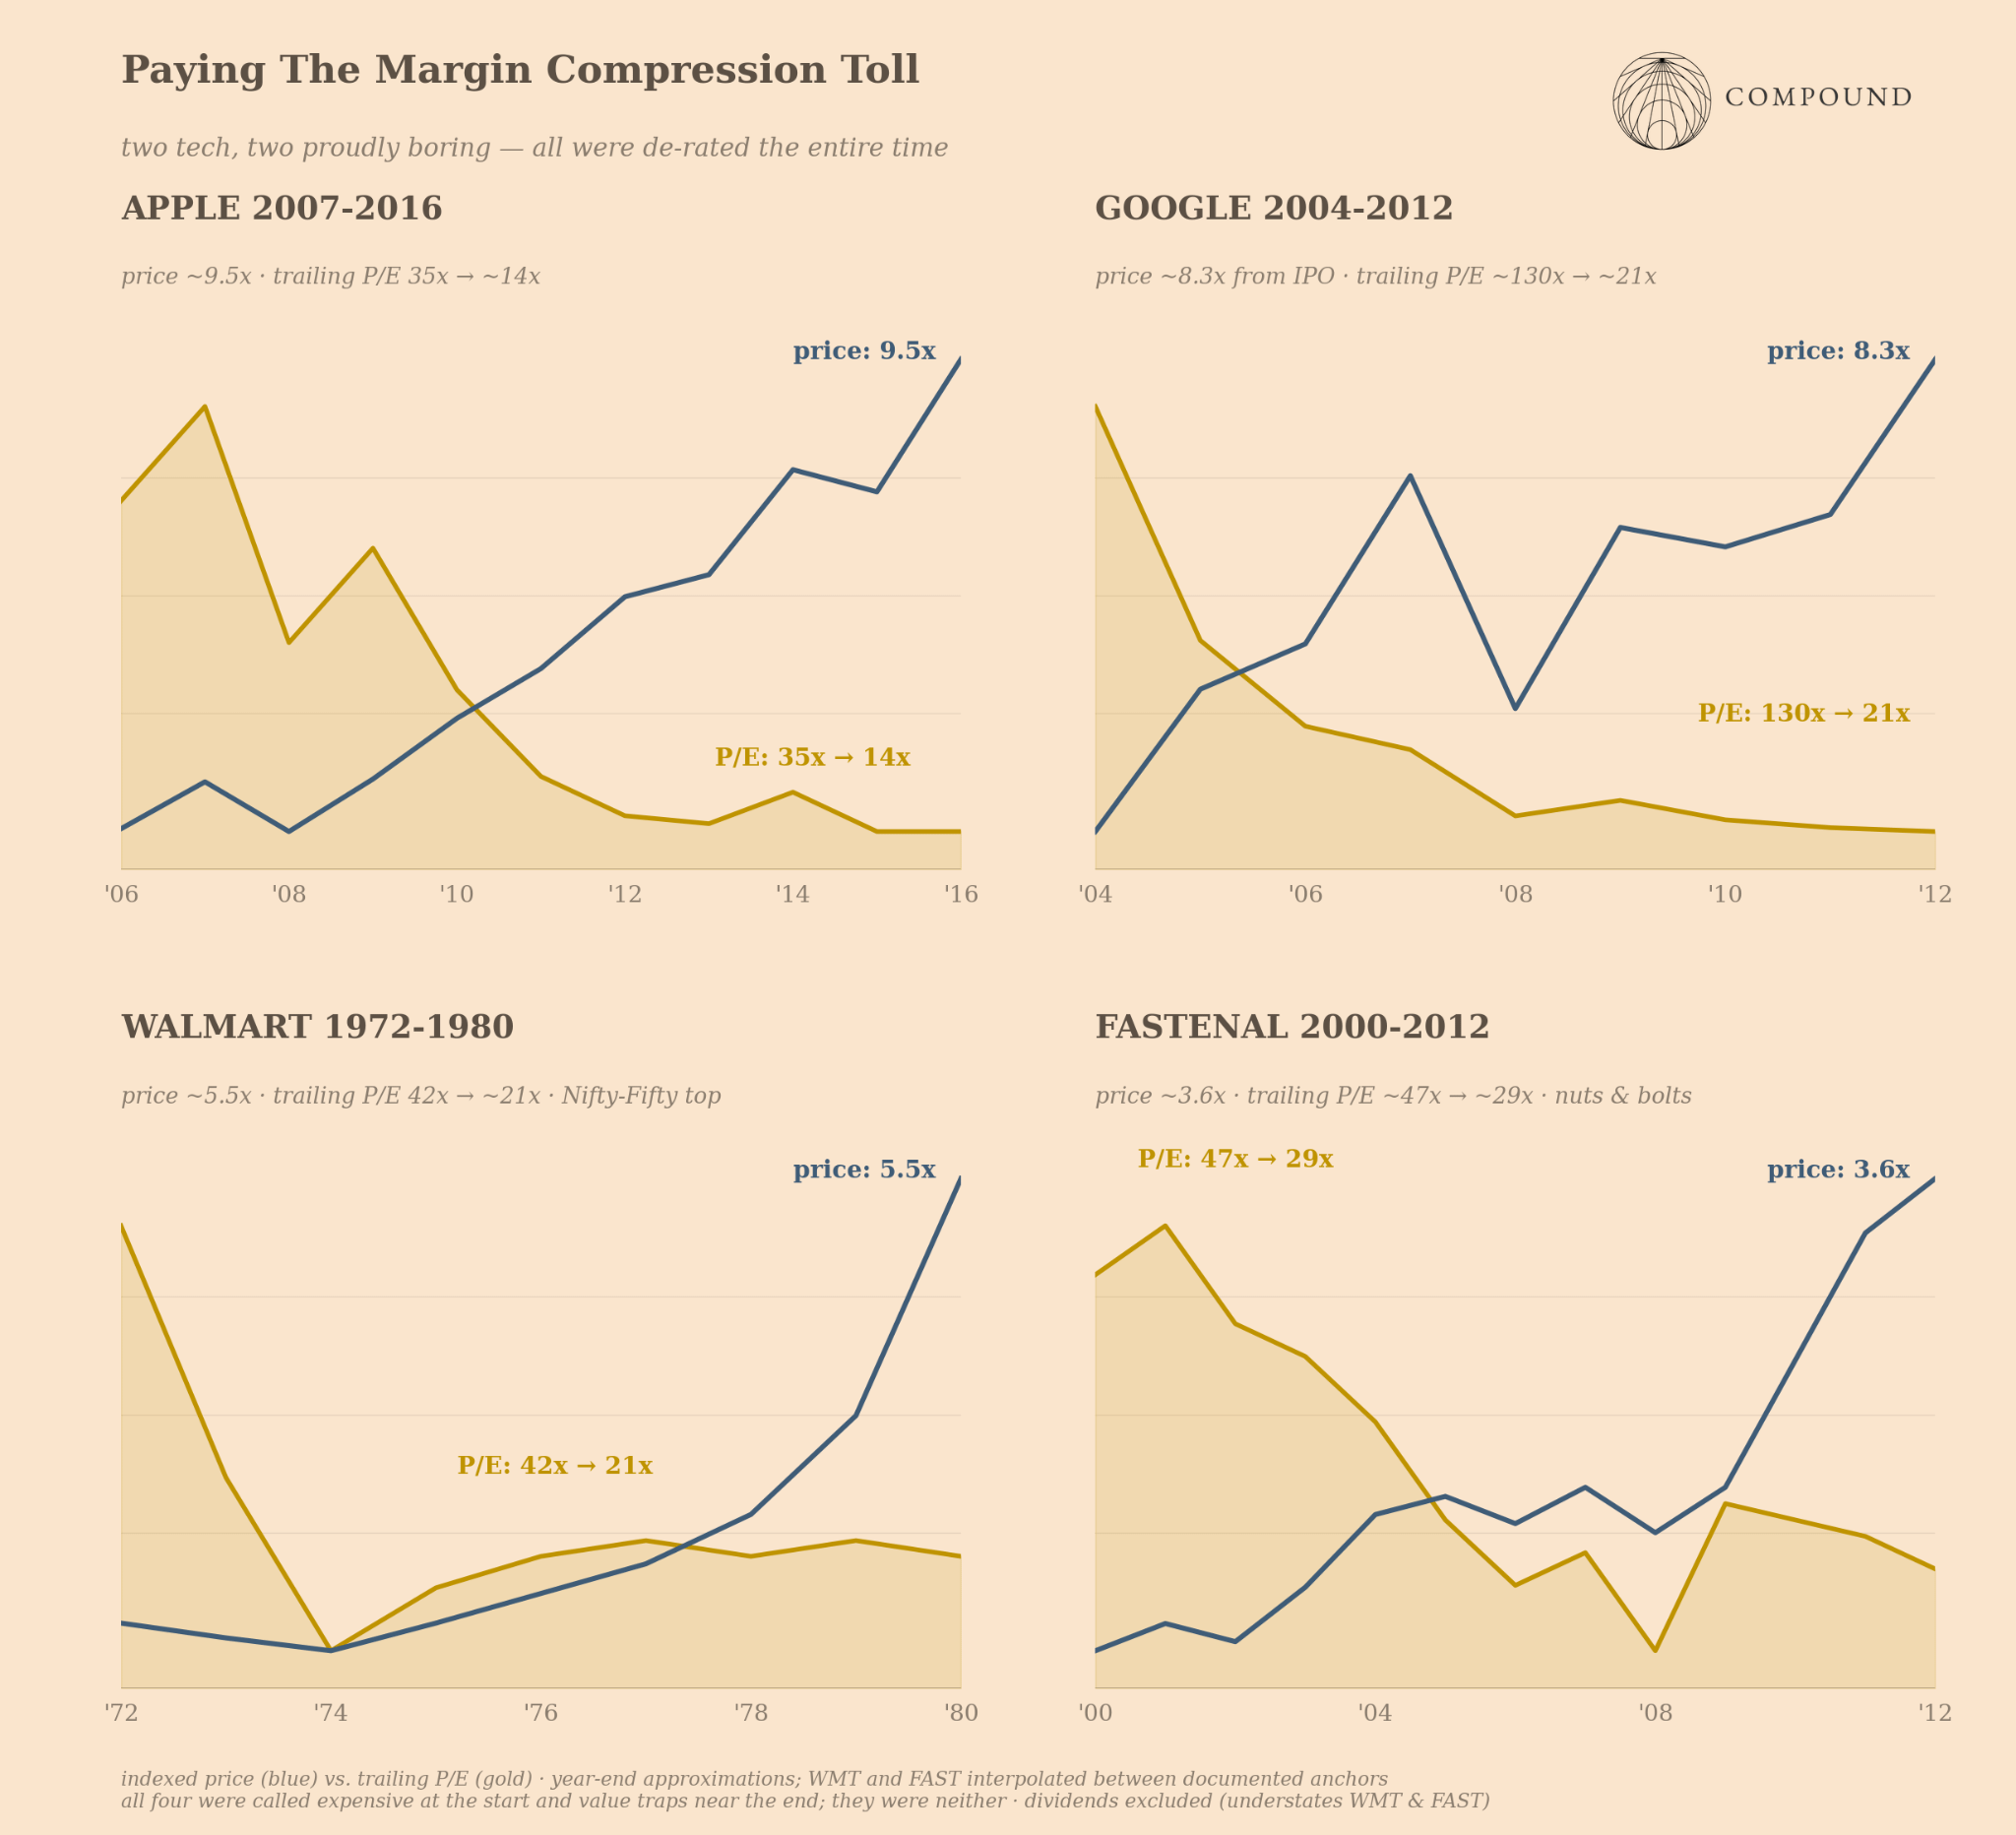
The last point worth reiterating is that the common error for each is some different form of failing to disentangle the two variables inside the multiple. You have two groups making duration mistakes in opposite directions (i.e. underweighting long runways or long declines) and two groups making quality-attribution mistakes in opposite directions (attributing category quality to the wrong asset or applying some emotional taint to a “clean” asset).
So Is This Going To Persist?
I actually think it’s going to accelerate. There’s one argument to be made that markets are becoming more efficient as fewer humans are making the decisions and we now have access to near-infinite data. But I don’t buy this. If anything, they’re becoming more inefficient and the world is becoming more volatile. This whole perception-vs-reality dispersion isn’t some artifact of a bygone market era. And I’d be surprised if we don’t see the gap widen over the next 5-10 years.
The market’s composition has shifted toward businesses where the muddying of fundamentals and growth is higher than ever. Widget factories are a very different business model than what we see today (and will see in the future). Even the indices are inherently longer-duration today given the concentration at the top of them.
The convective regime I wrote about previously almost manufactures these Q2 & Q3 companies at industrial scale. Rolling narratives mean that whoever’s under the current storm is likely overshooting in both directions and each cell’s maturity kind of births a fresh cohort of these companies.
AI is simultaneously murdering the cheap version of the work and raising the price of the “real” or more difficult version. Everything screenable (multiples, comps, filings, transcript sentiment, etc) has been commoditized. The periods to harvest any alpha through data-driven methods is rapidly collapsing each time. But if we assume (hypothetically) everyone has the same perfect legible layer then the entirety of the edge comes from decision-making and judgment around the illegible layer.
Private markets are absorbing a larger share of some of the most extreme examples of these companies. These things are not continuously priced and so the multiple debate gets hidden, temporarily.
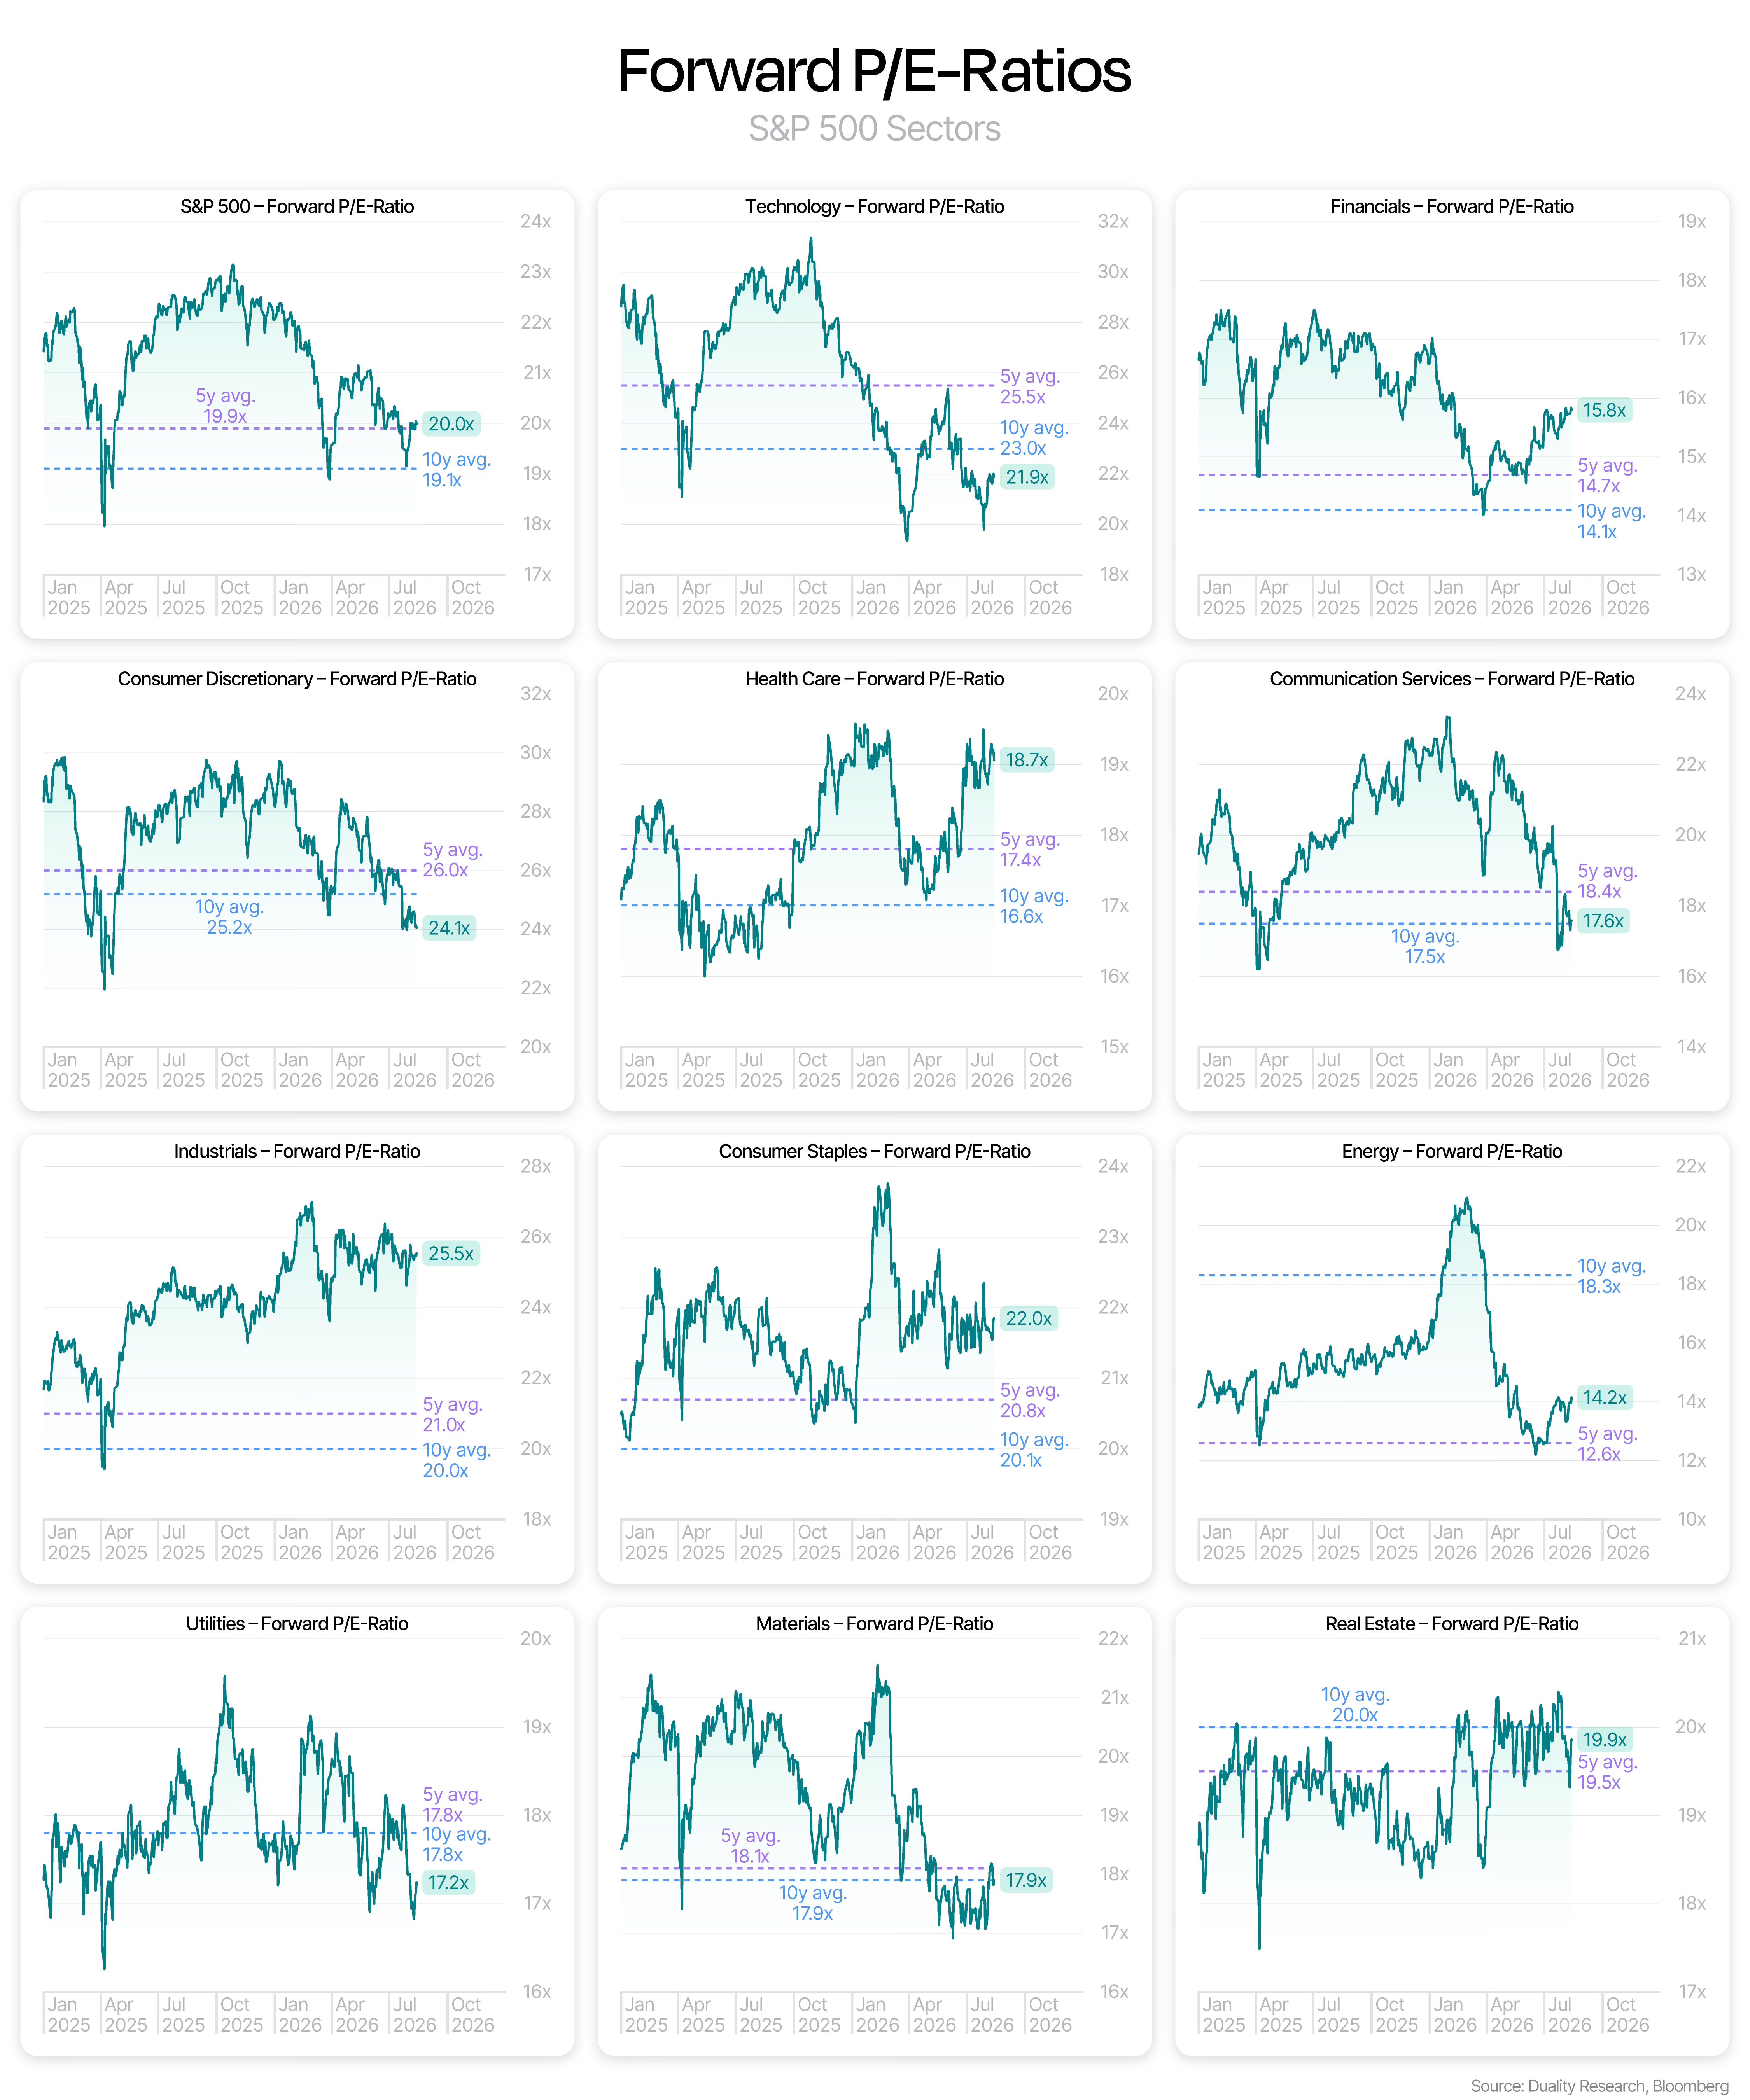
There are a lot of reasons today is a unique moment in time. But even as I was writing this, my inclination was to say “in today’s world the greatest risk is that we’ve got all these companies we think are seemingly expensive but will grow beyond the existing expectations”. I’m not sure that’s actually true though. Mostly because, at least in public markets, these companies are not historically expensive.16 These companies have grown earnings at almost unfathomable rates and so we’ve actually seen multiples come in.17 That’s the good news.
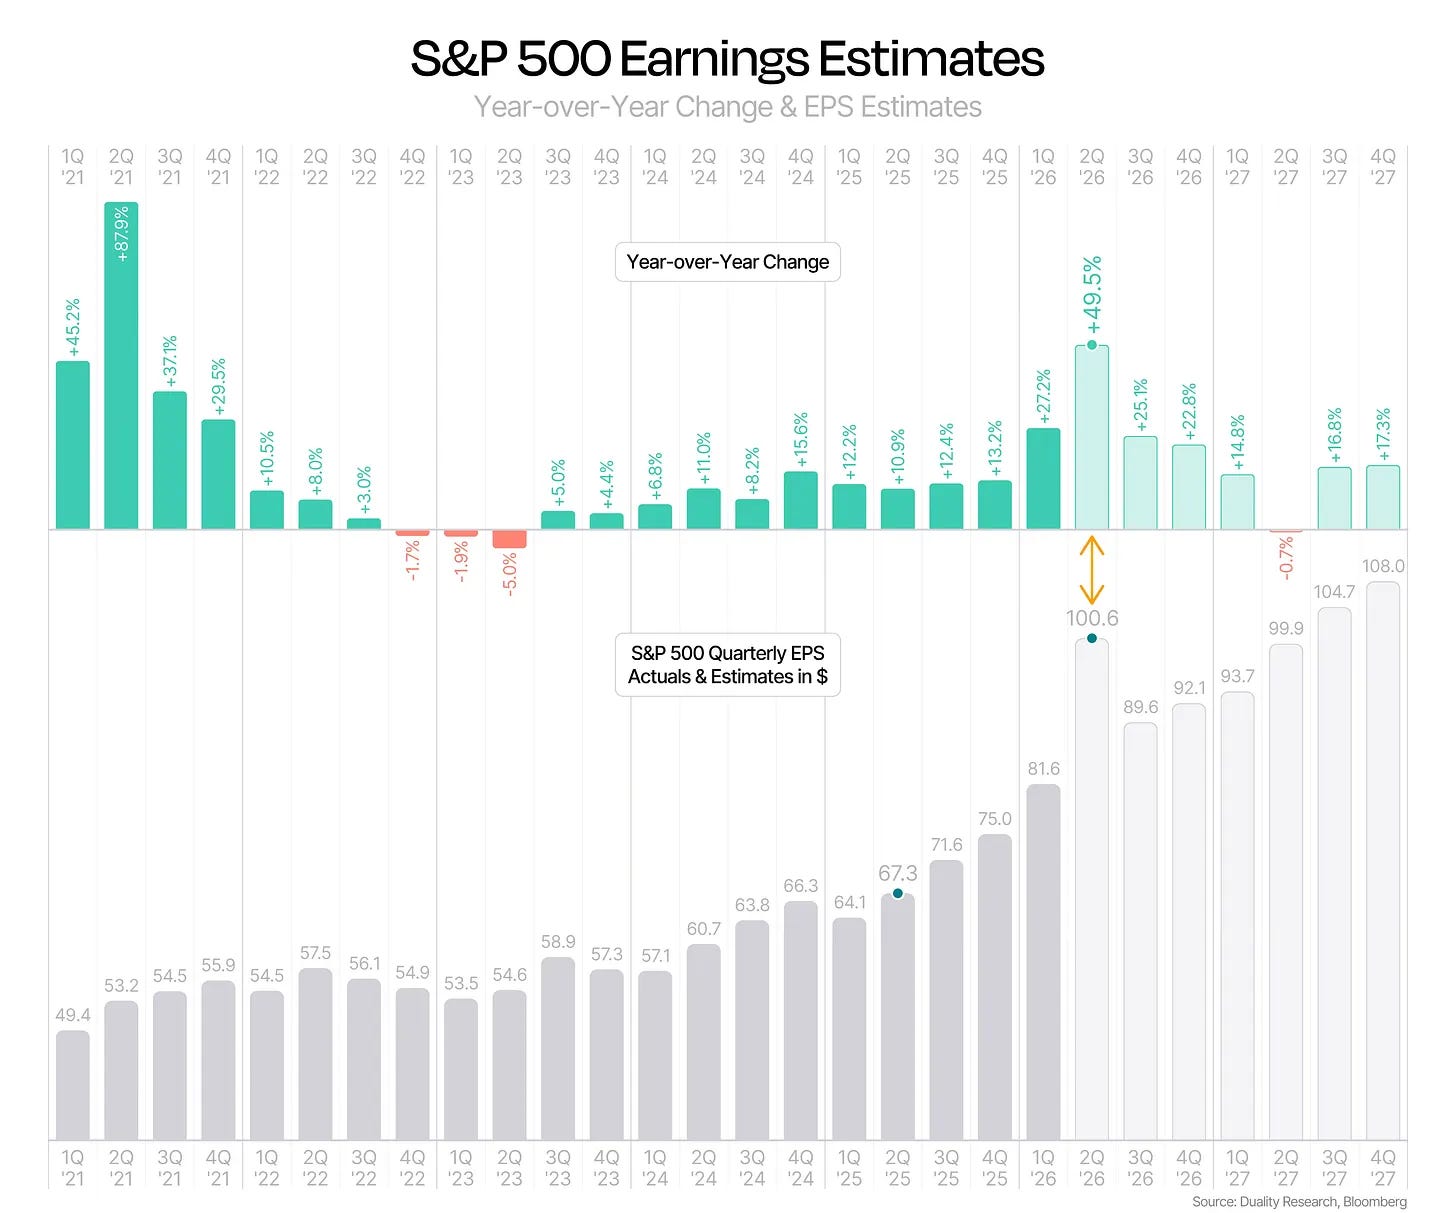
The bad news is that if we’re past peak growth, then what? Would you anticipate multiples expand in a world where growth is slowing? Do you believe we are truly on the precipice of sustained 8% GDP growth? Do you know the last period in US history where that happened? Is this time different? I’m being intentionally provocative here because the reality is that the world is complex, and I imagine it will remain so. There’s a lot happening out there beyond AI.
Every high profile founder, investor, media brand and philosophizer is incentivized to perpetuate the story that taking valuation risk (i.e. Q1) is a necessary part of the new game today. It keeps dollars flowing. It lets people say things like “we are democratizing intelligence”. It raises the stakes for the eventual game of chicken. But it’s also tilting the board toward momentum-style investing. Which is a much more fragile game to play when we’re talking about physical world constraints and supply chains as opposed to SaaS businesses. There’s a lot of embedded leverage in this complex and a lot of long-duration assumptions. Even slight hiccups in timing or scale would have a meaningful impact across the chain.
It’s possible everything works. That would be ideal. But regardless of whether we get euphoria or dystopia, the path-dependent nature of markets means that we are almost surely going to look back in 5 or 10 years and laugh about [abc] company at [xyz] forward multiple. The only question is what type of laugh it will be…
ty to mike, jmo & BR for feedback & help crystallizing ideas
Disclaimer:
The content on this site is for educational and informational purposes only. Nothing presented above is intended to make an offer to or solicitation to sell or purchase securities or interests. It is not intended to be a substitute for professional advice. Investing involves risk, including the possible loss of principal.
intrinsically brighter in the sense that they were actually brighter regardless of how they were seen from earth
i’m being a bit hyperbolic as the fundamentals of most of the big tech co’s have been excellent
true across the US and 12 of 13 broad-based international markets
Ken French data library
Ben Graham and Warren Buffett most famously. Buffett famously incepted an annual pilgrimage of investors to Oklahoma every year to hear from Oz
when asked about moats in this emerging world, it’s not a coincidence Sam began with the idea of scale: “brilliant intelligence can migrate from any product to any other product. And network effects still have a competitive advantage. Economic scale and the ability to make the cheapest compute fleets, whatever, still have a competitive advantage.”
one caveat is that there’s a point at which the market discounts the multiple for these huge companies despite the growth simply because of the law of large numbers. something we’ve seen with NVDA imo.
it’s a bit amusing to be that everyone largely agrees on the 80/20 rule and yet we don’t see companies firing 50%+ of their workforce every year
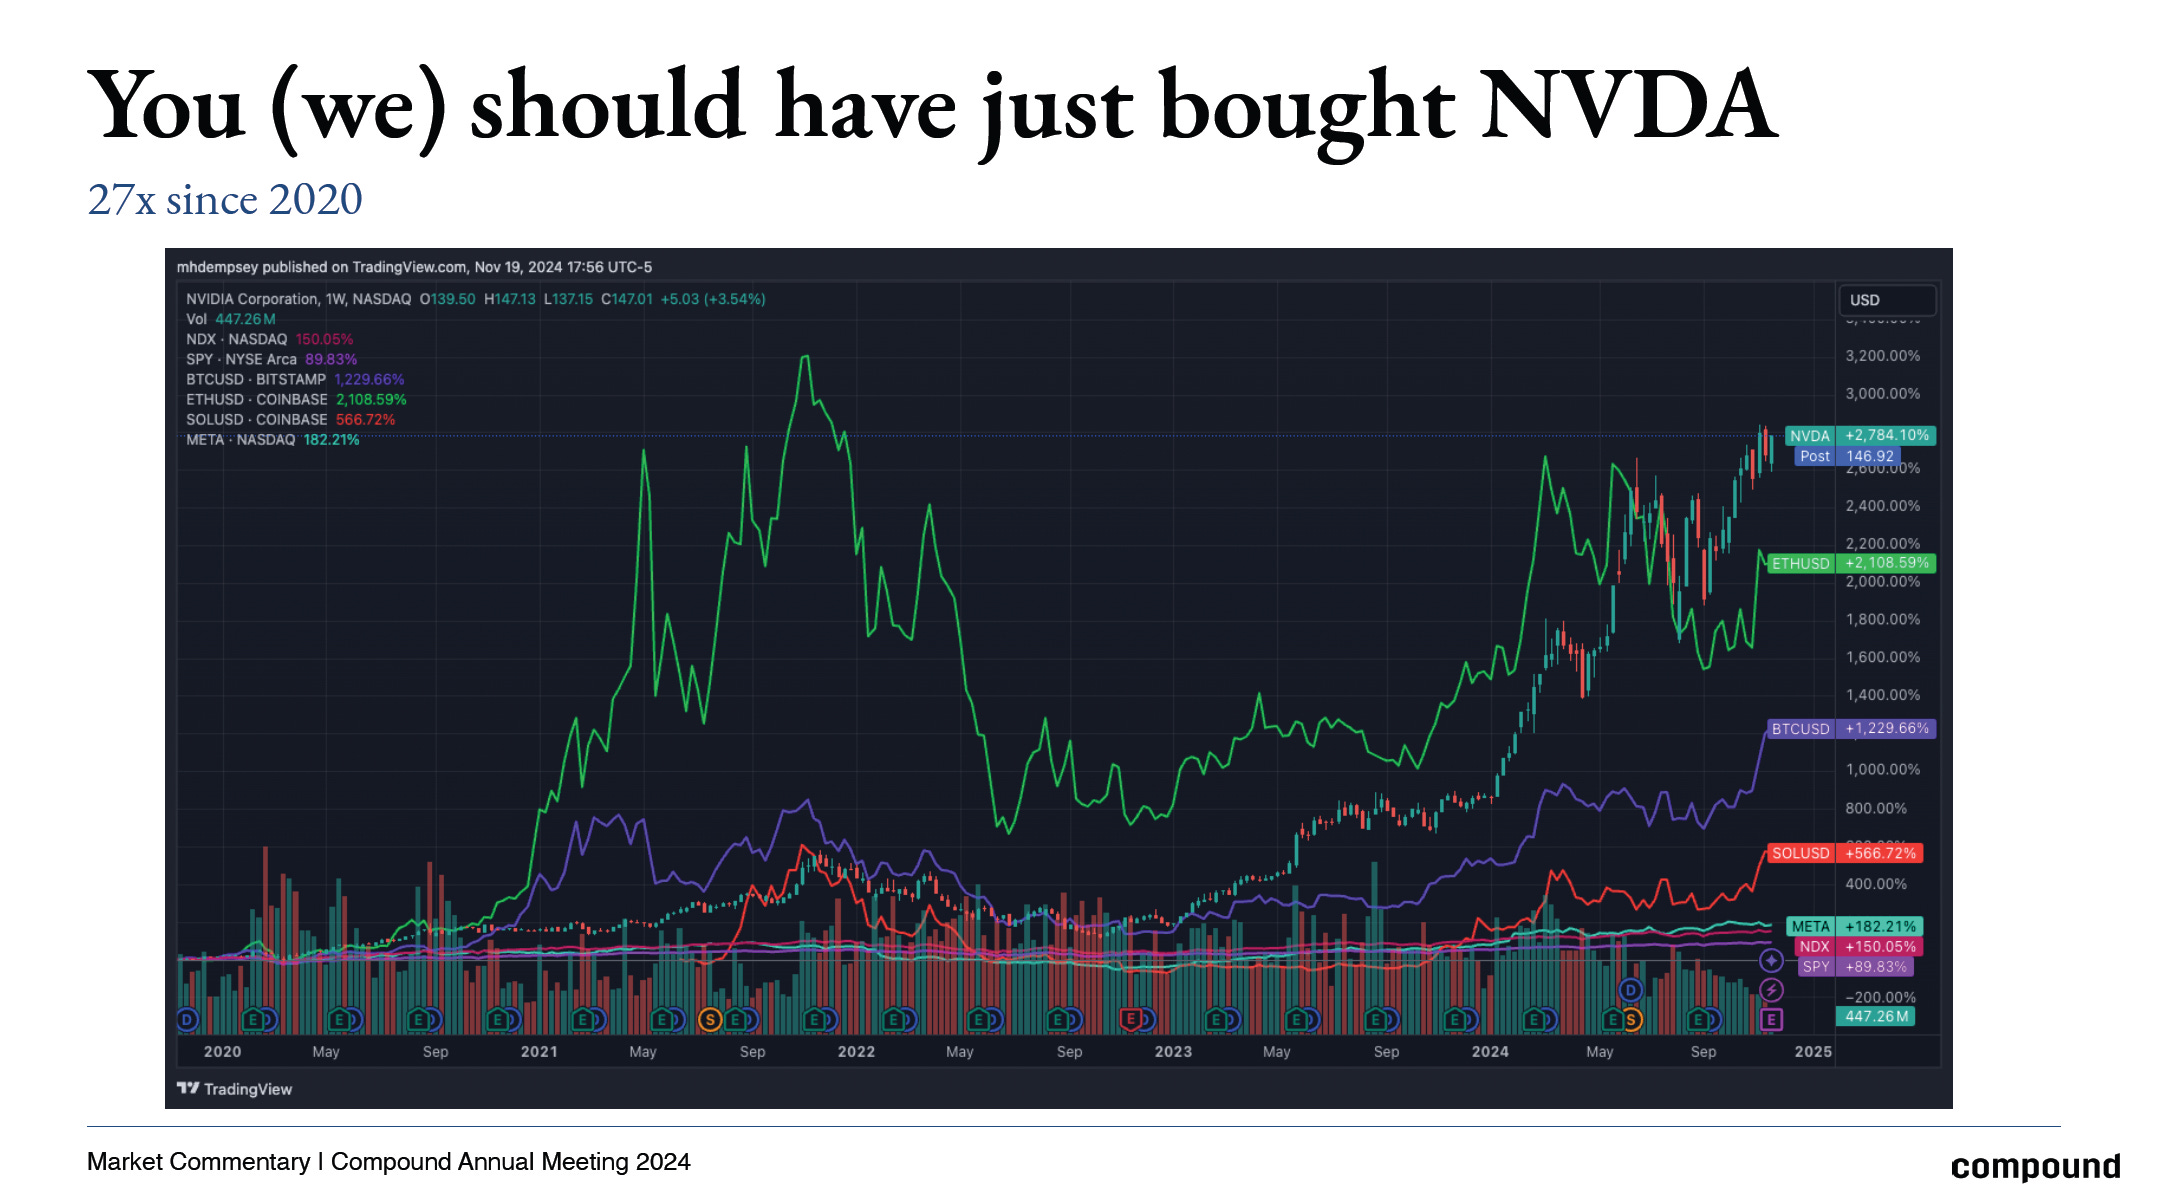
it is obviously easy to say now that you should have just owned NVDA the last 15 years but that’s the whole point. 15 years from now people will say “yOu sHoUld hAvE jUsT oWnEd ____”
this is also why we see tops form around “good” news and bottoms form around “bad” news
after it had already had its first blowout data center guide, the stock doubled and trailing multiples looked insane
even then the market cap was ~40% bubble peak
i’m generalizing
NVDA basically went sideways for 2 years from July ‘24 to last month despite executing as well as anyone could have hoped
One argument that I have for hyperscalers getting bigger is that a larger share of GDP will be driven to the cloud. This includes the 80% of the economy that is barely touched by software and tech. That is currently changing. It will be interesting to see how much of the new reindustrialization will require cloud - autonomy, robotics, computation and analog converting to digital.
Take Google 2026. It is undervalued relative to its peers and the market thinks it is losing and there are reasons for that. It's AI talent is leaving and they are perceived to be behind on LLMs and it is as yet unclear how AI search will impact traditional search. It could be argued that search is getting unbundled and specialized and a new market for pricing access to data and information needs to and will be stood up at some point because most of the traffic to websites is being intermediated by agents now. Adwords is potentially not relevant to that new mechanism and marketplace and that would impact the cash machine.
As you state, a lot of value investors missed Google, Meta and Apple despite the fact that these things were FCF machines. Warren Buffet being the most famous value investor to miss them because he didn't fully understand them. Had there ever been anything that rhymed with these businesses in the past? There is also something to the idea that the market signals and responses that were key to value investors have become muted or nonexistent because of HFT and passive investing. Will that ever come back? The market has shown that retail investors have the ability to move them.
You should include Micron in 2016 ($7) on your quadrant diagram (Q3). That stock was range bound from $2-$25 for 2+ decades with the exception of 2000. Even then you still might have done okay. There is a lot of emotional damage there. After 2016, it continued to have cyclical booms and busts over the next ten years but the secular trend was upwards because it was the need for memory and storage (mobile and cloud) continued to increase steadily until April 2025 ($65) at which point it exploded because of LLMs. While it is likely the cyclical nature of memory will rear its head again and the earnings potential may not continue, the floor is certainly higher.
wow